By Stella Odueme
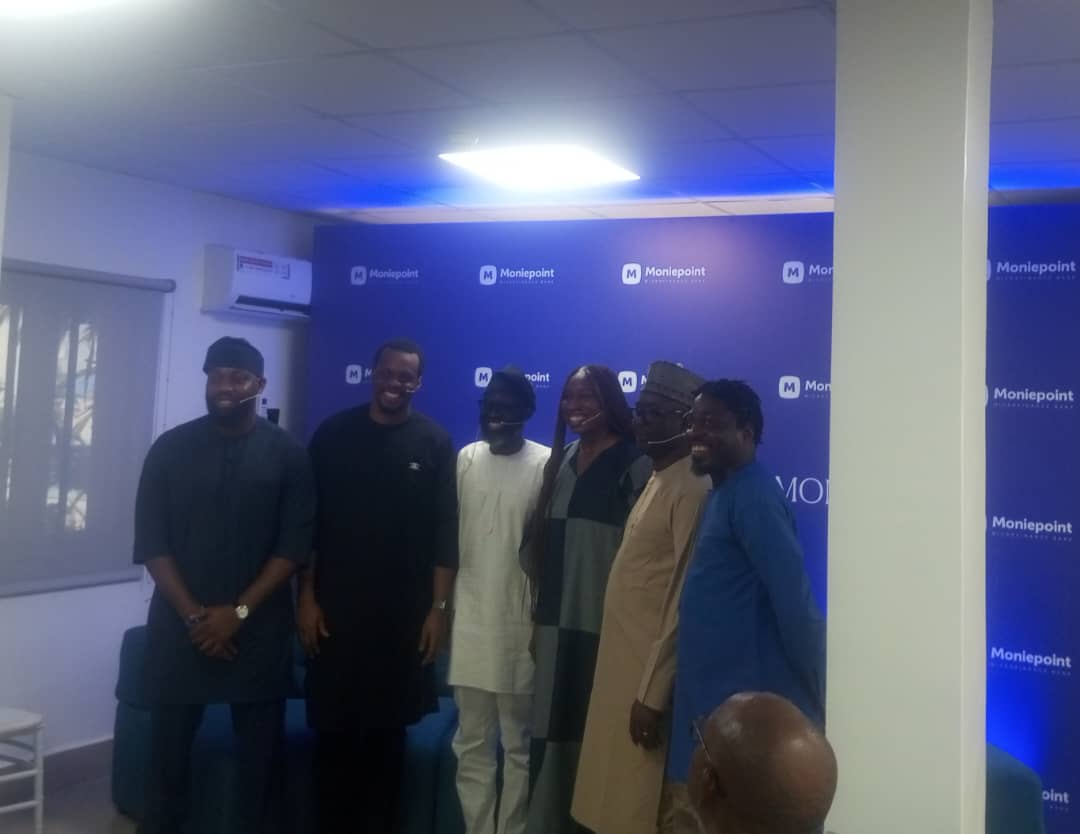
Vice President Kashim Shettima has inaugurated Moniepoint Microfinance Bank’s North Central regional headquarters in Abuja, urging the financial institution to expand access to affordable credit for small businesses, farmers and other underserved Nigerians.
Shettima, who was represented by the Minister of Finance, Taiwo Oyedele, gave the charge on Friday, during the inauguration of the facility.
He said the investment aligned with President Bola Ahmed Tinubu’s administration’s efforts to deepen financial inclusion, promote enterprise development and expand economic opportunities across the country.
The Vice President congratulated the bank’s board, management and employees on the investment, but stressed that the real value of the facility would be determined by its impact on businesses, job creation and the livelihoods of Nigerians.
“We are commissioning a building today. Its lasting value will be measured by the businesses it helps to grow and the opportunity it brings closer to our people,” he said.
He explained that access to affordable financing would enable traders to sustain their businesses, farmers to obtain resources for cultivation and artisans to acquire equipment to improve productivity.
“Finance makes a difference when it helps people move from what they can imagine to what they can achieve,” Shettima stated.
According to him, Nigeria must move beyond providing access to financial services to creating opportunities that enable citizens to generate income, build wealth and improve their standard of living.
“So we have to move from financial access to economic opportunity,” he said.
Shettima identified women entrepreneurs, young business owners, rural communities and enterprises operating outside major commercial centres as priority groups that financial institutions should deliberately support.
He commended Moniepoint’s approach of combining digital banking solutions with physical customer engagement, noting that technology alone could not address every challenge confronting users of financial services.
“Technology offers speed and reach, but people also need someone who can explain, listen and help when difficulties arise because they do arise,” he said.
The Vice President urged the bank to strengthen its customer relations framework through personalised assistance, clear communication and efficient complaint resolution mechanisms.
He maintained that customers should be able to understand banking charges, operate their accounts and resolve complaints without requiring advanced financial knowledge.
“A customer should not need to acquire advanced financial skills or knowledge to understand a charge, how to use an account or resolve a complaint,” he added.
On agricultural development, Shettima called on Moniepoint to extend its lending activities across the entire agricultural value chain, including production, aggregation, processing, logistics and marketing.
He explained that farmers required timely financing to purchase agricultural inputs and fund cultivation, while agro-processors needed capital to acquire machinery, establish storage facilities and secure regular supplies of raw materials.
He also highlighted the financing requirements of transport operators and agricultural traders responsible for moving farm produce from production centres to consumers.
The Vice President stressed that agricultural lending should reflect the peculiarities of farming, including planting and harvesting seasons, weather conditions and fluctuations in market prices.
“A farmer needs finance that understands the farming calendar. A processor needs finance that understands the production cycle,” he said.
He advised the bank to collaborate with agricultural cooperatives, insurance providers, produce off-takers and other industry stakeholders to improve access to financing for farmers and agribusinesses.
On credit accessibility, Shettima urged financial institutions to reduce borrowing costs, noting that interest rates, additional charges, repayment schedules and loan processing periods could determine whether financing supports or undermines small businesses.
“Affordability involves the interest rates, the fees that we charge, the repayment period, and time spent securing even that facility itself,” he said.
He explained that financial institutions could lower lending barriers by improving operational efficiency, adopting better credit assessment mechanisms and ensuring transparent pricing structures.
Shettima also highlighted the importance of digital transaction histories in evaluating businesses without conventional collateral, noting that such records could provide lenders with useful information for making credit decisions, subject to customers’ consent and adequate safeguards.
He identified Moniepoint’s MoneyBook business management platform as another tool that could help entrepreneurs monitor transactions, calculate expenses and manage cash flow.
Beyond providing loans, he urged the bank to equip business owners with practical financial management knowledge, including distinguishing revenue from profit, separating personal finances from business accounts, identifying applicable tax incentives and meeting tax reporting obligations.
On consumer protection, the Vice President warned that the expansion of digital banking must be accompanied by stronger safeguards against financial fraud, unauthorised transactions and other forms of abuse.
“Inclusion must be built on trust. Customers must be confident that their money is safe, their information is handled responsibly, and the terms of a product are clearly explained,” he said.
He called on the bank to intensify public awareness campaigns on account security, protection of financial credentials, detection of suspicious communications and procedures for reporting fraudulent activities.
He also emphasised the need for accessible complaint resolution channels, insisting that customers should be able to contact the bank easily and receive regular updates on reported problems.
“When something goes wrong, people need an accessible route to resolution. They should know who is handling their complaints,” he said.
Earlier, the Managing Director of Moniepoint Microfinance Bank, Babatunde Olofin, said the institution remained committed to extending financial services to more Nigerians through technology-driven operations and customer-focused products.
Olofin disclosed that the bank processed daily transactions exceeding N1 trillion and provided financial services to more than 21 million customers nationwide.
He also said its operations and support for businesses had contributed to the creation of over one million jobs across the country.
“With a daily transaction volume of over N1 trillion, Moniepoint has become a systemic and household bank in Nigeria, supporting over 21 million customers and providing more than one million jobs in the country,” he said.
Describing the institution’s ownership structure, Olofin said Moniepoint was established and managed by Nigerians.
“Moniepoint is proudly Nigerian, owned by Nigerians and managed by Nigerians. I think that deserves a round of applause,” he stated.
He attributed the company’s growth to sustained investments in technology and the development of financial products tailored to the needs of business operators and individual customers.
The managing director acknowledged the continued patronage and confidence of customers, particularly users of its digital banking platforms, Point of Sale (POS) terminals, mobile applications and other electronic payment channels.
He said products such as instant settlement services and working capital facilities had strengthened the bank’s appeal among businesses seeking reliable financial solutions.
Olofin explained that the Abuja headquarters represented a strategic effort to complement the bank’s digital operations with physical locations where customers could receive direct assistance and interact with business relationship managers.
“Today, we are expanding beyond digital banking to give every Moniepoint customer a welcoming space to walk into for face-to-face support, real-time assistance for their online businesses, and direct engagement with our business relationship managers,” he said.
He added that the establishment of physical offices would bring banking services closer to customers while improving convenience, service delivery and confidence in the institution.
The managing director disclosed that the bank planned to extend the initiative to more states by establishing additional offices to strengthen its nationwide presence.
“And this is just the beginning. We plan to open more locations across additional states as we bring even better services closer to you,” he said.
He reaffirmed the institution’s commitment to advancing financial inclusion and developing solutions capable of serving Nigerians across different social and economic backgrounds.
“We look forward to building financial happiness for every Nigerian, regardless of your origin or status,” he said.
Olofin further explained that Abuja was selected because of its strategic position in the North Central region, which connects the northern states and serves as an important commercial and administrative centre.
He described the North as a major business hub and an important food-producing region with a significant population, making it a strategic area for the bank’s expansion.
He said the decision to establish a physical presence in Abuja was driven by the need to strengthen customer trust, improve accessibility and bring services closer to millions of customers across the country.
According to him, Moniepoint’s expansion was also a response to the confidence customers had placed in its digital platforms, making it necessary for the institution to reciprocate through improved physical access and customer engagement.
He said the bank had served more than 30 million customers and processed trillions of naira in transactions daily, highlighting the importance of moving closer to its growing customer base.
Olofin noted that physical infrastructure would complement the bank’s digital platforms by providing customers with accessible locations for assistance, engagement and resolution of service-related issues.
In a separate statement on the development, Moniepoint said the new regional headquarters was part of its strategy to strengthen operational presence across North Central and Northern Nigeria.
The bank said the facility was designed to bring financial services, business support and digital banking solutions closer to small businesses, entrepreneurs and individuals, particularly farmers, agro-processors, traders and artisans.
It described Abuja as a strategic location because of its position as Nigeria’s administrative centre and a commercial link connecting the North Central region and other parts of the country.
According to the institution, the new hub would build on its existing network, which provides financial services to millions of entrepreneurs across all 36 states and the Federal Capital Territory.
The facility was designed as a multipurpose customer engagement centre combining digital banking services with physical interaction and personalised support.
Customers and business owners visiting the centre would have access to information and guidance on the bank’s financial solutions, including business banking, credit facilities, business management tools such as Moniebook, personal savings accounts, debit cards and payment products.
Moniepoint said the initiative was intended to strengthen brand trust, improve customer experience and humanise finanrcial services through direct engagement.
The bank reaffirmed its commitment to supporting Nigerian entrepreneurs and developing financial solutions that would help businesses grow, create employment and contribute to economic development.
